

Wisconsin’s hospital market grows more concentrated, report finds
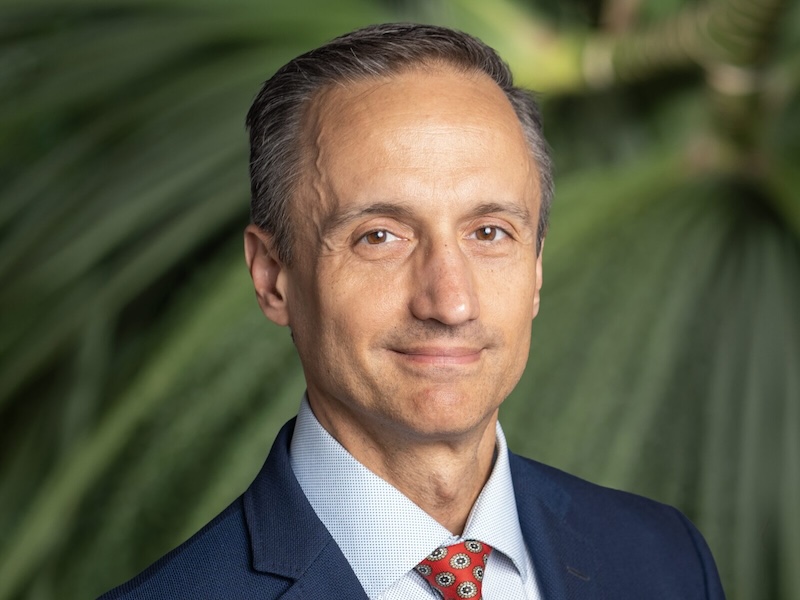
Wisconsin’s hospital market has become more concentrated in recent years, largely due to ownership changes, according to a report from a free-market think tank at the University of Wisconsin.
Anthony Lo Sasso, the UW public affairs professor who co-authored the study from the Center for Research on the Wisconsin Economy, said that concentrated markets limit a key tool insurers have to negotiate prices: the ability to cut hospitals from their networks.
“If you’re negotiating in the context of a highly consolidated market with maybe one or two big players, then that’s not a realistic threat because the insurer can’t sell a product without coverage for the dominant hospital and its affiliated providers in that market,” Lo Sasso said in an interview with Wisconsin Health News.
Consolidation “tips the scales” in favor of the hospitals being able to command higher prices, he said. Lo Sasso wrote the report with Ike Brannon, a senior fellow at the Jack Kemp Foundation.
In response, Wisconsin Hospital Association CEO Kyle O’Brien said the report attempts to “scapegoat hospitals” for high costs, while ignoring the profits of insurers and healthcare middlemen. WHA surveys show the state’s health systems had an operating margin of 2.2 percent on patient care in fiscal year 2024 and net losses in 2022 and 2023, when including non-hospital services, he noted.
O’Brien also said that CROWE’s report shows the Eau Claire market was highly consolidated even before Hospital Sisters Health System exited that region in 2024.
“If hospitals can dictate prices at the rate CROWE is trying to portray, why would two Chippewa Valley hospitals shutter their doors in 2024?” he said in a statement. “CROWE’s assertions simply do not reflect reality.”
WHA took issue with a previous CROWE report released in August that found inpatient hospital prices were 25.6 percent higher in Wisconsin than in Illinois, saying it wasn’t representative.
Lo Sasso said that they used national healthcare price transparency data and looked at high-volume procedures. Their methods are transparent and replicable, he said.
“If the hospitals want to show their math and how we missed something, they’re free to do that,” he said.
Lo Sasso and Brannon wrote in their report on consolidation that, beyond the Chicago area, Illinois’ hospital market is at least as concentrated as Wisconsin’s market, which suggests “more is going on in the Wisconsin healthcare market than meets the eye.”
Health plans owned by hospitals comprised 36 percent of Wisconsin’s fully insured commercial market in 2024, a figure that rises to 51 percent when counting Dean Health Plan, in which SSM Health holds a 45 percent stake, they wrote. In Illinois, one insurer has 62 percent of the commercial market, while provider-owned plans have 5 percent.
“The third act in the trilogy here, or whatever you want to call it, is to unpack the role of these provider-own plans,” Lo Sasso said. “Because now you’ve got a situation where it’s a health plan that is owned by the providers. Their goal is to keep patients within their walled garden of sorts, at the same time that they can possibly charge higher prices to competitor insurers.”
In response to the report, John Nygren, CEO of the Wisconsin Association of Health Plans, which represents provider-owned health plans in the state, said that Wisconsin ranks among the top states for insurance market competition.
“For all health plans — whether they are affiliated with a provider or are unaffiliated — competition creates consumer choice and encourages health plans to provide high-value care to consumers, focusing on affordability, quality, customer service and innovation,” he said in a statement.
Lo Sasso spoke to Wisconsin Health News this week. Edited excerpts are below.
WHN: Why are you digging into this issue?
Lo Sasso: I’ve lived most of my life in Illinois. Last January, I started here at Wisconsin. I was interested in the two healthcare markets, Wisconsin and Illinois. I wanted to learn more about it with a colleague who also used to work in Wisconsin and grew up in Illinois. That’s my co-author, Ike Brannon.
It started with a simple price comparison between the two states. There are more data available these days to allow for comparison of hospital prices. We took a look. That was the first report. We found to my surprise, and I think a lot of the people up here in Wisconsin that I’ve spoken to, that Wisconsin is a very expensive healthcare market. The prices are 25 percent higher on average than what you see in Illinois. That’s very striking, and it comports with national studies that have shown Wisconsin to be something of an outlier. I’ve joked with people (that) it’s like a fish doesn’t know it’s swimming in water. You’re inured to it because you don’t have a ready basis for comparison.
That intrigued me enough that I wanted to dive in a little deeper. The next logical step, at least to me as an economist, was to say, ‘What do the hospital markets look like in Wisconsin?’ That’s the second report that came out last week. I wanted to see if there was a substantial amount of merger activity and consolidation. Everything I found was consistent with my hypothesis that, yes, all the markets in Wisconsin are quite concentrated. They started concentrated, and they only got more concentrated in the time period that I looked at, which was 2018 to 2025. A lot of that was due to sequential merger activity, some more impactful when you look at one market versus another. That is at least partly consistent with the pricing differences.
WHN: What does Wisconsin do now that it has a concentrated market?
Lo Sasso: In my view, the truly durable solution to the issue of concentrated markets is to promote entry and competition as much as humanly possible, up to and including roles for government agencies locally and at the state level … That’s the way to rebuild competition. When you do that, you get reductions in prices as these competitors gain a foothold in the market and offer a viable alternative.
I’ll be honest. I called it the durable solution. It’s the slow road, but it’s the one that pays off the most down the line. Many of my health economist colleagues want to say, ‘We need to have price controls and more government involvement.’ I think that’ll give you an immediate sort of sugar high, but it won’t be sustainable. We know how this works. We have years of experience in the economics field, political economy and political science to know that regulators get captured by the industries that they regulate and wind up setting their own prices. It’s a tempting path, but I think it’s the wrong one. The better one is to look for ways to spur as much competition as possible.
WHN: Are you planning additional studies beyond the one on provider-owned health plans?
Lo Sasso: I don’t want to say no. I do want to take seriously the idea that, to be crude, it’s not all price gouging. The hospital perspective on this is going to be, ‘We are able to provide better care coordination, higher-quality care and better patient tracking within this environment.’
What would be other offshoot studies? Well, it would be to look at quality of care and what these prices are buying. Give the hospitals the benefit of the doubt and say, ‘Well, here’s my trilogy. Prove me wrong.’ These higher costs and higher premiums, everybody pays. Throughout the state, we all pay it. I’m a state employee. We buy these plans. Small businesses buy these plans. Large businesses have to pay these prices. We’re all on the hook for this one way or another. So, I would put the question back to them: What are we getting for our money? And is it worth it?
This article first appeared in the Wisconsin Health News daily email newsletter. Sign up for your free trial here.